Introducing Fairness in Business and Investment

This is a version of my speech from the (very enjoyable) London launch event of my book, on October 29th 2026. A version, because as I spoke without notes so these aren’t the exact words that I actually said!

When I first worked in the City, I wasn’t actually working in the City. Before we moved to Portsoken Street, Hermes’ offices were just along from here, on the east side of Mansell Street, and the official bounds of the City ran straight down the middle of that street. It’s less stark now, but there are still streets in this area where you can see one one side of the street the steel, glass and concrete and the wealth of the City, and on this side the bricks and mortar and the poverty of Tower Hamlets, where we are now. I know of no better symbol of the unfairness of our world, and how it gets oddly fixed and ossified than that the arbitrary choices of the Romans in choosing the boundaries of their settlement 2000 years ago are still reflected in a divide between wealth and poverty today. And this place, and the organisation it hosts, Toynbee Hall, works with the poor of this poor borough, and they often use the language of fairness talk about themselves.

That’s why we’re here.

Why we are here, though, is of course this little book, Fairness in Business and Investment. We all feel unfairness viscerally, and it’s not just that we here are a self-selected bunch. Rather, fairness is core to the human condition, it’s been a foundation of our social success as a species, it has been shown to be hard-wired in our brains, and been demonstrated to be present in children of ages all the way down to 15 months. And the thesis of my book is that when we as business-people and investors fail to be fair, we are not just denying something core to our humanity, we are worse at business and investment. For being fair delivers better business and investment, and delivers more prosperity for the long-term.
The book is in 3 parts, introductory, then fairness in business and fairness in investment.

As part of the introduction, I look at how consistent fairness is across cultures around the world. The ultimatum game shows this. I give XX £20 that she must share as she chooses it with YY – and they will get to keep their chosen shares if YY accepts what she’s offered. Economists argue that XX should make a low offer, and YY accept any money that is offered, because it’s free money (at least for you!). But of course that’s not how it works. Almost everywhere in almost all conditions, the most frequent offer, the mode, is 50%; the mean is often a bit lower, but still usually in the low 40s%; and offers below around 20% or 25% are almost always rejected. Fairness is shown to be – almost – universal. There is a key exception to the fairness shown by the ultimatum game, which I’ll come back to later.

Also in the introductory section, I discuss fairness of process, including the crucial issue of the Rule of Law. And I discuss fairness of outcomes, including the question of meritocracy. We all so love fairness that we want to believe that we live in meritocracies, and we’re often willing to believe that those who are suffering somehow deserve their misfortune, even when we happen to know for sure that’s not really true, and even when we doubt the genuine existence of meritocracy. I was at an event a couple of weeks ago and someone asserted that ‘no one believes in meritocracy any more’, in the sense that no one believes that we do live in meritocracies any more. But sadly that’s not true. Exactly the wrong people believe in meritocracy: those who succeed tend to, they believe they merit their success, think it is based on their skill and hard work alone, and are willing to ignore advantages they had or the role of just plain luck. And if they fall into that myth of meritocracy trap, it turns them into the most awful people. They drive aggressively, cutting up other traffic. They cheat in tests. They literally steal sweets from children. Successful people really can be awful human beings in their personal lives; who knows how they might act in their working lives?

The core of the book is the section on fairness in business. Here I look at each of the main stakeholder relationships, as set out in s172 of the Companies Act – employees, customers, suppliers, communities and so on. For each of them I consider what fairness looks like in relation to that stakeholder, what the benefits of fairness are, and something about the current state of play (usually not as good as it could be). I use the s172 list because I think it’s a useful articulation, not because I want to be narrowly British in the analysis – in fact when I share that ‘enlightened shareholder value’ approach with directors as part of the training I do, directors from around the world recognise it as a clear articulation of their duties, what they think the job of boards is, and what they think companies are there to do. And I show that even in the supposedly narrowly shareholder-focused US, actually the law properly understood is much closer to that articulation of enlightened shareholder value.

Of the s172 stakeholders, there’s probably least evidence for fairness making a valuable difference in the case of the environment. I think that’s because that relationship isn’t mediated through humans, and so isn’t subject to the push and pull between people that is often the source of fairness. But even there I find evidence of the need to strike a fair balance. And I go all the way down the list of s172 stakeholders, including corporate governance and good business conduct, and fair dealing with shareholders. I cover dual class shares, and the accounting and reporting wonks among you will be particularly pleased to know that I cover true and fair, as well as fair, balanced and understandable and Fair Disclosure (Reg FD) in that section. It’s striking how central fairness is to the language we use when we talk about the corporate relationship with its investors.

But it’s odd that we use fairness rather less in our expectations of investors themselves. So, to move to the final section of the book, fairness in investment. This section is rather less evidence-based and rather more aspirational than the fairness in business section. And the reason for this is that there is simply much less experience of fairness operating in the investment world, on which such evidence might be founded. Someone here’s employer has just launched an advertising campaign based on their being the fair pension and investment provider. While normally I love to see fairness in marketing, seeing it being applied as a core differentiator in the investment world depresses me a little.

And it’s here also that the outlier in the ultimatum game comes in: when researchers merely briefly called it a ‘Wall Street game’ when introducing the rules, the outcomes were very different, with initial offers much less generous and much greater acceptance of lowball offers. We fundamentally believe and accept that Wall Street, that the investment world, is less fair than the real world.

And that’s ironic because the foundation of all investment is the concept of fiduciary duties, that we’re looking after other people’s money and therefore must care for their interests above all. People in investment proudly talk about themselves as fiduciaries, as they should. And here’s the thing: fiduciary duties arise from that branch of the legal system known as Equity, which as the name suggests seeks to deliver fair outcomes whatever a strict interpretation of the law might be. So it is odd that investment, which is based on fiduciary duty, and so founded in equity, is not actually expected to be fair.

Fairness proves a valuable way to illuminate other key challenges in the investment world too, including stewardship, systemic risk and short-termism. The final nugget I’ll share is on short-termism, which we measure in investment using discount rates – the amount by which future money is worth less than money in the present. With the scale of our long-term problems, we desperately need to be thinking more long-term and so have lower discount rates, valuing the future more. But there’s a finding that in conditions of inequality – which obviously we are currently in – people have higher discount rates, they discount the future more and focus more on the present. There’s some logic to it, as inequality increases the risk that we may not be around to enjoy the future, and we may not have the funds to enjoy it. But the researchers argue that it’s more a psychological outcome than a logical one, and given that they’ve shown other psychological effects on discount rates (not least that men become much more short-term while in the presence of an attractive woman) it’s hard to argue with them.

So not only does unfairness exacerbate many of our future problems, it also constrains our ability – or at least how we perceive our ability – to deal with them.

So, in short, fairness matters to us as humans, deeply, viscerally. We miss something fundamental if we close our minds to it in our business and investment lives. Businesses need strong stakeholder relationships, all of which are stronger if mediated through fairness. Investment ignores fairness at its peril, risking the strength of customer (fiduciary) relationships, bringing systemic risks and limiting the ability to address them, getting timeframes wrong and too short-term, not least because of excess discounting. Yet we are human, and we shouldn’t allow the Wall Street game to have different fundamental rules to the rest of our lives, or be fooled by success within what we hope are meritocracies but really aren’t.

Fairness matters, and we will succeed more in business and for our investment clients, if we believe that and act more vigorously on it.

I’m happy to confirm as ever that the Sense of Fairness blog, and indeed Fairness in Business and Investment, are purely personal endeavours.
Baring the necessities

I fight shy of defining fairness. There’s a broad range of options that fulfil fairness for human beings – and different individuals will reach different judgements as to whether a particular circumstance falls within that range. There’s somewhat more clarity about unfairness. That concept animates us all so viscerally that we can more readily agree that something is unfair, even though there is much human judgement in that too.

This human and emotional side of fairness and unfairness is exactly why it is more rewarding to explore than the definable and measurable concepts of equality and inequality.

Such is the strength of my sense that I shouldn’t seek to define fairness that throughout my forthcoming book I provide no easy answers. Instead, I talk about ways in which businesspeople and investors can develop their own approach to finding a fair landing ground. I believe that the push and pull between people is so key to finding what is fair in any particular circumstance that making assertions in the absence of its particular details is all but impossible. It’s not by chance that the legal approach of equity is entirely based on reaching a fair outcome, setting aside any detailed legal rules: equity – fairness – can’t be defined in advance, successive courts have found, but only decided by judges considering the facts of the individual case. The same is true of fairness outside the court context: it must be subject to judgement based on the particular circumstances.

So I found myself baulking a little at those sections of Will Snell’s highly accessible new book The Fair Necessities that assert “Fairness is definable”. Indeed, for Snell, the CEO of the wonderful Fairness Foundation, the definition of fairness is based on his eponymous ‘fair necessities’ (which he and the Fairness Foundation first launched on the world in 2021). They are, exactly as he sets them out in the book:

  • Fair essentials: Everyone should have their basic needs met, but we need to go further to enable people to play a constructive role in society.
  • Fair opportunities: Everyone should be able to thrive, without having to overcome unreasonable barriers to opportunity or earn a huge salary.
  • Fair rewards: Everyone’s hard work should be rewarded, in line with their contribution to our society as well as to our economy.
  • Fair exchange: Everyone should contribute to society by paying their fair share in tax, and in return should be supported by society when they need it.
  • Fair treatment: Everyone should be treated with equal respect and should be able to exercise equal influence on decisions made in their name.

These seem to me a good articulation of key pillars of fairness, and key elements of what fairness might look like if delivered in practice. But a definition? Maybe not so much.

So I personally welcome the book’s later comments that fairness inevitably means different things to different people, and particularly comments acknowledging that really the fair necessities offer a framework for understanding fairness, and operationalising it in society – rather than a definition as such. Certainly, it was as such a framework that Snell spoke about the fair necessities at the book launch I had the pleasure of attending last month.

And it is really in that operationalisation of fairness that Snell’s book comes into its own, in a powerful and valuable way. Even as someone who has chatted with Snell over a number of years and closely followed the Fairness Foundation’s thoughtful work, I found much that was new in the book’s later chapters, especially the last substantive one, ‘Dismantling the barriers to fairness’. In particular, Snell discusses how to win the social and political argument about the need for greater fairness, and particularly highlights the need for an engaging and emotional discussion of fairness, not a purely technocratic one. Only occasionally does he fall into the trap of implying that the fairness agenda is favoured by people of one specific political persuasion; elsewhere he rightly notes that the concept works across the political spectrum.

Only deploying such an engaging and emotional discussion of fairness will, in Snell’s words, change the political wind, and help society acknowledge the scale of the risk that our current unfairnesses represent. I suspect his quote from economist Angus Deaton (from his 2024 Rethinking my Economics comments) will stay with me for some time: “Efficiency is important, but we valorise it over other ends … When efficiency comes with upward redistribution – frequently though not inevitably – our recommendations have become little more than a license for plunder.”

I’ve niggled about a small aspect of the book (though the posited definition is the frame within which its title is first explained) but really I would, very simply, highly commend The Fair Necessities to all. It’s accessible and challenging, and like this blog it is based on the clear understanding that our world needs, and deserves, more fairness. Do read it, do enjoy, and do think about how we collectively can more effectively operationalise fairness.

See also: Mother Nature’s recipes

Fairness: the human lens for addressing our current challenges

Deaton’s economics: fair criticism?

I’m happy to confirm as ever that the Sense of Fairness blog is a purely personal endeavour.

The Fair Necessities, Will Snell. Policy Press, 2026

The Fair Necessities: Why we need a fairer Britain and how to make it happen, event at Policy Institute at King’s College London, 8 September 2026

Rethinking my economics, Angus Deaton, International Monetary Fund blog, March 2024

A just AI transition?

Even given my cynicism regarding the current hype about artificial intelligence (AI)*, I have to admit that it’s very clear this new technology will transform the world of work. The societal excitement about Chat GPT and other large language models (LLMs) has been matched by corporate excitement. Companies across the world are experimenting broadly, many of them keen to deploy this as a cost-saving tool.

Of course, as with every technology shift, cost-saving comes in the form of replacing people with machinery. Efficiency means being able to do things more quickly with less human intervention. If the current experiments with AI deliver, perhaps companies will redeploy those humans to other work. More likely they will remove those people, and their costs, from their business.

That’s how business, and economies as a whole, operate: moving to more efficient ways of delivering what customers and society want, to enable higher profits or simply to enable companies to compete with rivals which are also trying to reduce their costs. On the whole, this is good for economies too as more efficiency allows national resources to the deployed to where they deliver most value.

But that redeployment takes time, and technology transitions are painful processes, for individuals and for society. Discussions of efficiency, cost savings or redeploying resources divorce us from the very real human and emotional impacts of these changes, which are of individuals losing their jobs and livelihoods, and subsequently struggling for money and self-esteem. Even where a technological shift does create new opportunities (which has been the case with every such transition previously and so seems likely once again), that takes time – time in which individuals feel unanchored, unvalued, and perhaps reach an age where further employment is unavailable to them. That can serve to destabilise society further. We shouldn’t let the economics blind us to the personal and emotional.

There is much talk in sustainable investment circles of the need for a just transition (sometimes a fair and just transition) to a decarbonised world, ensuring that care is taken to protect and support those individuals whose jobs are impacted by the dramatic shift to economic activity that must come as the world finally faces up to the realities of climate change. There is also likely to need to be a fair and just transition to an AI-enabled world.

Recent work from the International Monetary Fund (IMF) begins to open a window on this challenge, building on the sentiment of managing director Kristalina Georgieva in a blog from a year ago called AI Will Transform the Global Economy. Let’s Make Sure It Benefits Humanity. The organisation is developing approaches to consider which jobs – and which economies overall – will be impacted by the advent of AI.

Most recently, IMF staff considered impacts in Asia. A blog this month, How Artificial Intelligence Will Affect Asia’s Economies, tries to map this out in more detail, based on analysis of the breakdown of jobs in each economy. The blog reflects a deeper discussion within the analytical note attached to the Fund’s most recent Asia and Pacific Regional Economic Outlook. This analysis suggests a greater exposure to AI impacts in the region in what IMF jargon terms advanced economies, while emerging economies are likely to face lower impacts. However, they also seek to assess whether those impacts will be positive or negative for jobs: around half the impacts in advanced economies are where AI is complementary to the job, potentially driving economic benefits; meanwhile in emerging economies the majority of impacts are where there is much more likelihood of workers finding their jobs replaced. The economists hedge this analysis with language such as ‘low complementarity’ and ‘displacement’ of work, but the thinking is clear.

The language was more blunt in some earlier less detailed work, suggesting AI “could endanger 33 percent of jobs in advanced economies, 24 percent in emerging economies, and 18 percent in low-income countries”. Those conclusions look more worrying than the most recent analysis, but even the lower levels of estimated disruption are very significant.

According to the most recent analysis, there is also a gendered split in the potential impacts, again potentially exacerbating existing inequalities:

The blog reads:

“The concentration of such [complementary] jobs in Asia’s advanced economies could worsen inequality between countries over time. While about 40 percent of jobs in Singapore are rated as highly complementary to AI, the share is just 3 percent in Laos.
“AI could also increase inequality within countries. Most workers at risk of displacement in the Asia-Pacific region work in service, sales, and clerical support roles. Meanwhile, workers who are more likely to benefit from AI typically work in managerial, professional, and technician roles that already tend to be among the better paid professions.”

Georgieva was clear about the risks: “In most scenarios, AI will likely worsen overall inequality, a troubling trend that policymakers must proactively address to prevent the technology from further stoking social tensions.”

The IMF economists are increasingly clear about what needs to be done about these inequality risks. According to them, a just transition will require:

  • Effective social security nets
  • Reskilling programmes for affected workers
  • Education and training to enable effective application of the AI opportunity, particularly for those economies where AI is currently seen to have low impacts – so that the positive benefits can be enjoyed
  • Regulation to promote ethical AI use and data protection

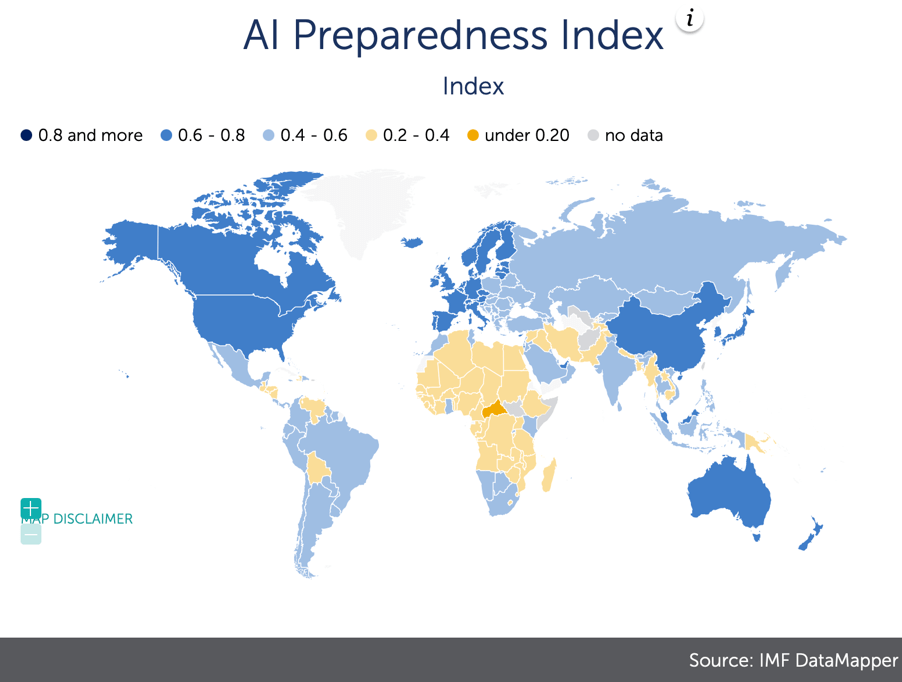
The IMF, in its AI Preparedness Index, suggests that there is a broad spread in the readiness of global economies for this coming wave of technological disruption:

Again, as things stand it seems that the greatest likelihood is for AI to exacerbate existing inequalities. Preparing for this major economic shift will demand fresh policies and investment. These are significant challenges for world economies, for companies as they embed AI into their workflows, and for global investors, to rise to.

See also: Learning from the stochastic parrots
Amazon resurrects worst of the industrial revolution
Just transitions and gilets jaunes

*I have my doubts about each of the A and the I in artificial intelligence: calling an activity ‘artificial’ when it depends on the horrific grinding work of many people to scrub its results seems inaccurate; and calling it ‘intelligent’ when it is simply a logic puzzle about the likelihood of putting one word after another – the stochastic parrots as described in that prescient article (I particularly like the analogy of Emily Bender, one of the authors of that article and a professor at the University of Washington, that AI is reproducing text in the way people might if they had unrestricted access to the National Library of Thailand but without pictures or dictionaries to enable them actually to understand or translate the language). A more recent article touching on these matters is the excellent Ask me Anything! How ChatGPT got Hyped into Being, which among other things states this fundamental truth: “LLMs are not designed to represent the world. There is no understanding by the artificial agent (chatbot) of the meaning of the output it creates. It is us humans who create that meaning.” More directly, the word soups that I have been presented with by colleagues show very clearly the limits of the technology in doing anything without clear instruction and precise pre-existing materials to work with.

See also: What’s a fair use?

I am happy for confirm as ever that the Sense of Fairness blog is a purely personal endeavour.

AI Will Transform the Global Economy. Let’s Make Sure It Benefits Humanity, Kristalina Georgieva, IMF, 14 January 2024

How Artificial Intelligence Will Affect Asia’s Economies, Tristan Hennig, Shujaat Khan, IMF, 5 January 2025

Asia and Pacific Regional Economic Outlook, IMF, November 2024

Thought experiment in the National Library of Thailand, Emily Bender, Medium, 25 May 2023

Ask me Anything! How ChatGPT got Hyped into Being, Jascha Bareis, 2024

Data and inequality

Long-term readers will know that I have my doubts about the value of the precise measurement of inequality known as the Gini coefficient. It’s one of the specific examples of my general cynicism about overly specific measurements. Things are usually a good deal more complicated.

Nonetheless it is fascinating to read John Burn-Murdoch’s piece for the Financial Times this weekend, Inequality hasn’t risen. Here’s why it feels like it has, which is grounded wholly in the Gini coefficient. Burn-Murdoch is the FT’s Mr Statistics, and he is always readable and interesting, so I’ll forgive the obsession with the use of single datapoints that will always be flawed if viewed in isolation (and I’ll acknowledge also that he recognises the limits of Gini: “Aggregate inequality statistics certainly have their place, but they can mask important nuances,” he writes).

The core of Burn-Murdoch’s article is the data shown in these charts:

He notes the increased attention to inequality over the past decade, even though the Gini numbers suggest it is in fact falling in both the UK and US, and he attributes this to a squeezing of the middle class between improved treatment of the poorest paid (which appears to be the driver of more than the total drop in the Gini measurement) and an increased stretching of the advantages of those best off in our society (which has increased inequality, but less than the reduction driven by the improvements for those least well off). While it’s known that the minimum wage in the UK and its bolstering over time has helped those least well off here, it is more surprising to find that some similar improvements have also been experienced by the poorest in the US also, despite the notorious stagnation of the national minimum wage there. This squeezing effect is reflected in the title given to the article in the paper copy of the newspaper: Why the middle class is right to feel squeezed.

This blog would naturally suggest that one reason why there is increased noise about inequality now, despite the falls in the Gini coefficient, is that the problem as humans see it is unfairness, not inequality, and the bluntness of Gini fails to capture the richness of human experience. In particular, it’s hard to believe that the improvement in the incomes of the poorest is genuinely felt to be an improvement in their life experience – perhaps especially as they have experienced greater inflation than wider society over recent times. The moves in Gini may be masking insight as much as they are revealing.

Burn-Murdoch is clearly right when he highlights the reductions in sense of opportunity available to many in society – opportunity both for themselves and for their children. But, for this blog at least, these are questions of fairness, not of inequality (measured by Gini or in some other way).

See also: Fairness – the human lens for addressing our current challenges
What gets measured gets managed – unfortunately
The centre cannot hold
Inflation’s two separate world’s (at least)

I am happy to confirm as ever that the Sense of Fairness blog is a purely personal endeavour.

Inequality hasn’t risen. Here’s why it feels like it has, John Burn-Murdoch, Financial Times, 4 January 2025

Deaton’s economics: fair criticism?

It is remarkable that the International Monetary Fund, one of the bastions of our modern economic construct, should be so willing to test and challenge current economic thinking. But that is what it does in publishing a striking short blog by respected economist Angus Deaton. Deaton is best known for his remarkable work on the US epidemic of what he has dubbed deaths of despair and he also led a recently-completed eponymous review of inequality for the Institute of Fiscal Studies. Deaton offers what amounts to an apologia for modern economics, and suggests some routes that may be more productive for the future. Not only might they be more productive, I would suggest that they are also likely to be fairer.

In the blog, Deaton questions mainstream economics. He does so from a remarkably mainstream position. He won the Nobel Prize in 2015, and is a professor at Princeton. His criticism of the failings of current economics, and not least of current economic education, should therefore hit home.

The core of Deaton’s points are made in crisp discussions under a handful of bullet-point headings. These are: power, philosophy and ethics, efficiency, empirical methods and humility (doesn’t our entire world need a whole lot more of that last?). He comes most crisply to his point in the first of these: “Without an analysis of power, it is hard to understand inequality or much else in modern capitalism.” But the bullet points reflect a continuity of thought, not separate ideas. He complains at the loss of ethical thought from economics and its replacement by an emphasis on efficiency and a simplifying focus on the financial: “We often equate well-being with money or consumption, missing much of what matters to people.”

Under efficiency, he states:

“Many subscribe to Lionel Robbins’ definition of economics as the allocation of scarce resources among competing ends or to the stronger version that says that economists should focus on efficiency and leave equity to others, to politicians or administrators. But the others regularly fail to materialize, so that when efficiency comes with upward redistribution—frequently though not inevitably—our recommendations become little more than a license for plunder.”

I think that quote bears rereading.

Applying these five approaches as a new lens for approaching questions, Deaton reaches a range of fresh conclusions – or rather a reduced level of certainty – about a number of different issues. These include: unions, free trade, global poverty and immigration.

But though it is not among these bullet-points, or the issues about which Deaton now has less certainty, to my mind one of the most notable single words in the piece is ‘efficacy’. Deaton says: “today we [economists] are in some disarray. We did not collectively predict the financial crisis and, worse still, we may have contributed to it through an overenthusiastic belief in the efficacy of markets, especially financial markets whose structure and implications we understood less well than we thought.” Normally economists and investors talk about market efficiency, and certainly the financial crisis was in part due to overconfidence that markets are efficient, that they will find the right prices for things. The efficient market hypothesis – which many investors take as a certainty, even though it is merely an hypothesis, and even though there would be no ability of active investors to outperform if it were true (admittedly many are more lucky than genuinely generate outperformance, but nonetheless it is still possible to outperform a market). The crisis showed that market pricing can often be very wrong and the use of market prices as a foundation for valuations can be risky.

Deaton is clearly referencing the Efficient Market Hypothesis (and the use of ‘efficiency’ as one of his bullet-point headings makes more notable his decision not to use the term in his comment about the disarray of modern economics), but he is actually making a very different point. He is asking whether markets are always efficacious, whether they work and always add value to human society. And his clear view is that they are not always, and do not always. We should listen, particularly those of us who work in financial markets.

Deaton has never minced his words, but here he is remarkably cruel about his profession. He says he does not want to get into the question of corruption among his peers, though he notes that allegations “have become common in some debates”. But he does state, bluntly: “economists, who have prospered mightily over the past half century, might fairly be accused of having a vested interest in capitalism as it currently operates”. In a blog that clearly has real concerns about the operation of modern capitalism, that fair comment is one that should hang over the profession, challenging all to rethink with the confidence and honesty that Deaton has.

See also: Meritocracy’s unfair

I’m happy to continue to confirm that the Sense of Fairness blog is a purely personal endeavour.

Rethinking my economics, Angus Deaton, International Monetary Fund blog, March 2024

Rising morbidity and mortality in midlife among white non-Hispanic Americans in the 21st century, Anne Case, Angus Deaton, Proceedings of the National Academy of Sciences, Vol 112 No 49, December 2015

Deaths of Despair and the Future of Capitalism, Anne Case, Angus Deaton, Princeton University Press, 2020

Deaton Review of Inequality, Institute of Fiscal Studies